
Canberra Insurance Brokers: Your Guide to Finding an Insurance Broker in Canberra
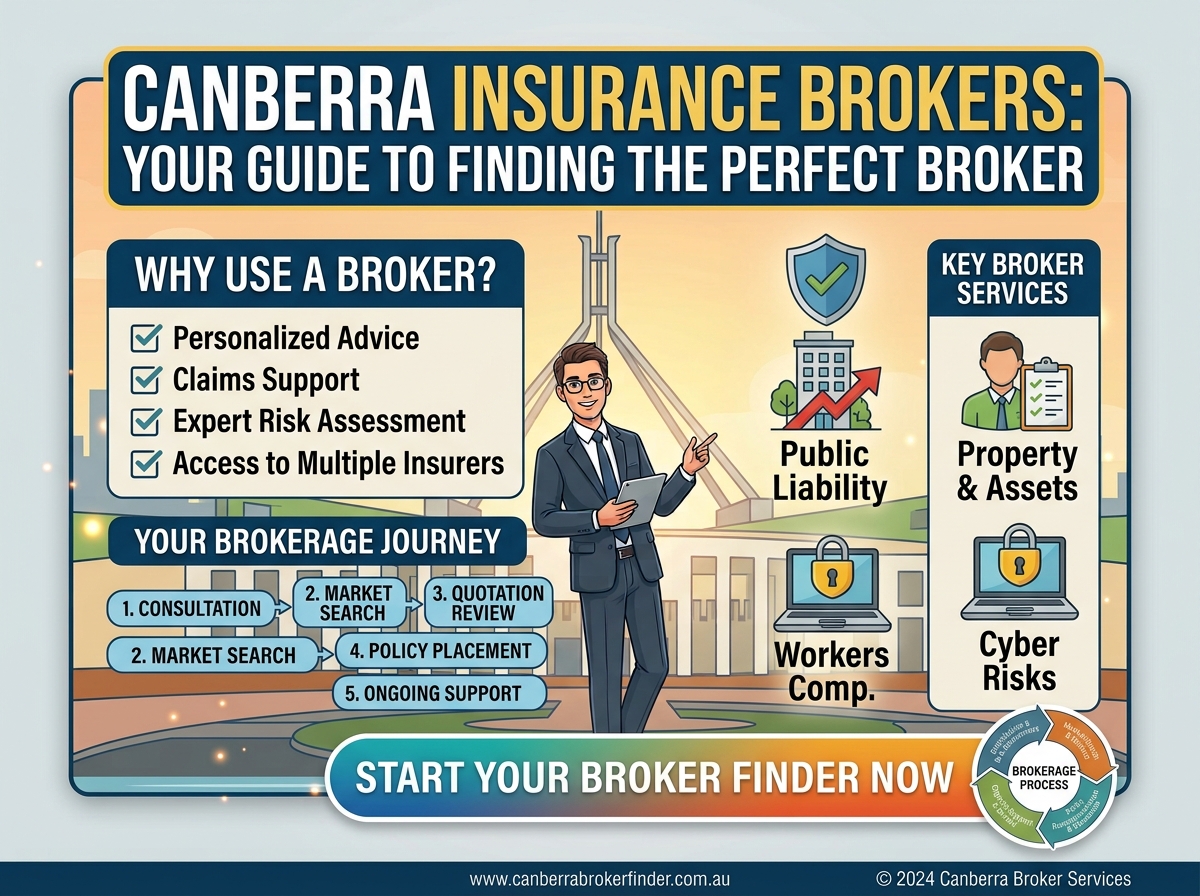
Finding the right insurance can sometimes feel more complicated than it needs to be.
There are different insurers, policy types, coverage limits, exclusions, excesses and Product Disclosure Statements to consider. Then there is the question many people start with:
“Which insurance broker near me can help me choose the right cover?”
For individuals, landlords, tradespeople, professionals and businesses across Canberra and the Australian Capital Territory, an insurance broker can help make that process easier to understand.
A broker can help you identify the types of insurance relevant to your circumstances, compare available options and understand important differences between policies. Australian Government business guidance notes that insurance brokers can access policies from multiple insurance companies and recommends checking the broker's Australian Financial Services (AFS) licensing status through ASIC's professional register.
The important thing is not simply finding an insurance policy.
It is finding insurance that matches your actual risks.
For a Canberra business, that could mean public liability, professional indemnity, business insurance, commercial property, cyber insurance, commercial motor, business interruption or other covers.
For a landlord, property and liability considerations may be more important.
For a professional consultant, professional indemnity may be a priority.
For a tradie, public liability, tools, equipment and vehicle insurance could be important.
That is why working with an insurance broker in Canberra can be useful when your insurance needs become more complex.
What Does an Insurance Broker Do?
An insurance broker acts as an intermediary in arranging insurance and helping clients understand available insurance options.
Rather than simply choosing the first policy that appears online, a broker can help you work through questions such as:
- What risks does my business face?
- What insurance do I actually need?
- How much cover should I consider?
- What exclusions should I understand?
- What excess applies?
- Does my client contract require specific insurance?
- Are my existing policies still suitable?
- Have changes to my business created insurance gaps?
The Australian Government recommends talking with registered insurance companies and brokers when managing business insurance and says brokers can access policies from multiple insurance companies.
Why local knowledge can matter
Insurance is not purely about location, but understanding the local business environment can make conversations more relevant.
Canberra includes government-related businesses, professional services, construction and trades, retail, hospitality, technology companies, property businesses, consultants and many small businesses.
That means there is no single insurance package suitable for every business operating in Canberra.
Why Search for Canberra Insurance Brokers Instead of Buying Insurance Alone?
Online insurance has made it easier to obtain quotes, but getting a quote is not necessarily the same thing as understanding your coverage.
A policy can look attractive based on price while having conditions or exclusions that matter to your particular circumstances.
For example, a business owner may ask for public liability insurance but discover that they also need to think about professional services, products, equipment, vehicles or business interruption.
A technology company may need cyber insurance as well as professional indemnity.
A property owner may need commercial property and liability cover.
A contractor working on government or commercial projects may need particular insurance limits specified in a contract.
A broker can help you look at the overall picture rather than treating each risk as an isolated purchase.
Insurance Broker Canberra: What Types of Insurance Can a Broker Help With?
The exact products available will depend on your circumstances and the insurers involved.
For Canberra businesses and property owners, common insurance categories include the following.
Business Insurance
Business insurance in Canberra can bring together several forms of protection based on the nature of your operations.
Depending on your business, this may include:
- Public liability
- Property
- Contents
- Business interruption
- Equipment
- Product liability
- Professional indemnity
- Cyber insurance
- Commercial motor
- Management liability
The Australian Government identifies property, liability, professional indemnity, product liability, business interruption and cyber insurance among the types of cover businesses may need to consider.
The key is understanding which risks actually apply to your business.
Public Liability Insurance Canberra
Public liability insurance can help protect a business against certain claims involving third-party injury or property damage arising from negligence.
For example, a customer might be injured while visiting business premises, or a contractor could accidentally damage a client's property while completing work.
Business.gov.au explains that public liability insurance can cover certain claims involving death, injury or property damage caused by negligence.
Who should consider public liability insurance?
It may be relevant to:
- Builders
- Electricians
- Plumbers
- Carpenters
- Landscapers
- Cleaners
- Retailers
- Cafés
- Restaurants
- Fitness businesses
- Event companies
- Consultants
- Contractors
- Tradespeople
It is also important to understand that public liability is not a replacement for every other type of business insurance.
Professional Indemnity Insurance Canberra
Professional indemnity insurance is particularly relevant to businesses that provide advice, professional services or specialist expertise.
Business.gov.au explains that professional indemnity insurance can help cover legal action arising from claims against professional advice or services, including mistakes, neglect or certain breaches of contract.
Professionals who may consider professional indemnity include:
- Accountants
- Lawyers
- Consultants
- Architects
- Engineers
- IT professionals
- Financial advisers
- Designers
- Marketing consultants
- Project managers
- Other professional service providers
Some professions may have specific insurance requirements, so businesses should check their industry obligations.
Cyber Insurance Canberra
Cybersecurity is no longer only a concern for large technology companies.
Small businesses increasingly rely on:
- Cloud software
- Online banking
- Websites
- Customer databases
- Accounting platforms
- CRM systems
- Online payments
- Digital documents
A cyber incident can interrupt normal operations and create costs associated with responding to the event.
Business.gov.au explains that cyber insurance can address certain costs associated with cyber extortion, ransomware, business interruption, network security, data breaches and recovery, depending on the policy.
Why Canberra businesses should consider cyber risk
A business does not have to be a cybersecurity company to be exposed to cyber incidents.
If your business depends on digital systems, it is worth reviewing both your cybersecurity controls and whether insurance is appropriate.
Cyber insurance should complement, rather than replace, security measures such as strong passwords, multi-factor authentication, backups, access controls and employee awareness.
Commercial Property Insurance Canberra
Commercial property owners have different risks from businesses that simply rent an office or shop.
Commercial property insurance can be used for relevant buildings, contents and other insured property, subject to the policy.
A property review should consider:
Building
What would it cost to repair or rebuild the property following an insured event?
Contents
What furniture, fixtures and other contents would need to be replaced?
Equipment
Does the business depend on expensive machinery, computers or specialist equipment?
Stock
Would the current policy adequately reflect the amount of stock normally held?
Business interruption
How would the business cope financially if an insured event temporarily stopped operations?
These questions can help identify potential gaps before a claim occurs.
Business Interruption Insurance
Physical damage is only part of the problem following a major business incident.
Imagine a fire damages your premises and the business cannot trade normally for several months.
Even if your property is eventually repaired, the business may continue to face expenses such as rent, salaries, financing costs and supplier commitments.
Business.gov.au describes business interruption insurance as cover that can help with ongoing business costs where an insured event interrupts the business, such as fire damaging business property.
Questions to ask about business interruption cover
What event activates the policy?
Make sure you understand which insured events can trigger a claim.
How long is the indemnity period?
Consider how long your business may realistically need to recover.
What income calculation applies?
Understand how the policy calculates an insured loss.
Are additional expenses included?
Some policies can provide cover for certain additional costs associated with reducing an interruption.
Insurance Broker ACT: Understanding Workers Compensation
For employers in the ACT, workers compensation is a particularly important area.
The ACT Government states that employers must maintain a current ACT workers' compensation policy with an approved insurer.
WorkSafe ACT also states that an employer in the ACT must have a workers' compensation insurance policy covering its workers and emphasises that workers compensation is separate from business and public liability insurance.
The ACT private-sector workers compensation scheme is privately underwritten by insurers approved by WorkSafe ACT.
Why this matters for Canberra employers
If you employ people, workers compensation should not be treated as an optional add-on to ordinary business insurance.
Your obligations may change as your workforce and business structure change.
WorkSafe ACT states that employers have responsibilities including maintaining a current workers compensation policy, meeting injury-management obligations and maintaining relevant workplace documentation.
For current ACT requirements, businesses should rely on WorkSafe ACT and obtain appropriate professional advice for their circumstances.
Insurance Brokers Canberra for Tradies and Contractors
Canberra has thousands of businesses operating in construction, maintenance, property services and other trades.
For a tradie or contractor, insurance requirements can involve several different areas.
Public liability
Protection against certain third-party injury and property damage claims.
Tools and equipment
Cover may be relevant to portable tools and business equipment.
Commercial vehicles
A work ute, van or truck may need appropriate commercial motor insurance.
Contract requirements
Principal contractors or clients may specify particular insurance limits.
Professional indemnity
Some contractors provide advice, designs or specialist services that could create professional liability exposures.
A broker can help review these areas together rather than looking at each policy independently.
Insurance Broker Canberra for Professional Services
Professional services businesses have a different risk profile.
A consultant may never have customers entering a physical premises, but they could still face a claim related to professional advice.
Consider a Canberra consulting business that provides strategic advice to a client.
If the client alleges that an error in the advice caused financial loss, public liability may not be the policy designed for that exposure.
This is why professional indemnity can be particularly important for professional services.
Businesses should also consider cyber, business interruption, property, contents and other relevant covers.
Insurance Brokers Canberra for Retailers and Hospitality Businesses
Retail shops, cafés and restaurants deal with customers every day.
That can create exposures involving premises, customers, equipment, stock, products and interruption to trading.
A hospitality business may need to consider:
- Public liability
- Products liability
- Property
- Contents
- Equipment
- Stock
- Business interruption
- Commercial motor
- Workers compensation
- Cyber insurance
The appropriate combination depends on the business.
There is no standard policy that automatically covers every risk.
Insurance Broker Near Me: What Should You Look For?
When people search “insurance broker near me”, proximity is often the first consideration.
But distance should not be the only factor.
A useful broker relationship should also involve clear communication, appropriate licensing arrangements, knowledge of relevant insurance products and an understanding of your circumstances.
1. Check licensing and authorisation
Business.gov.au recommends checking an insurance broker's AFS status through ASIC's professional register.
2. Ask about experience with your industry
Insurance for a construction company is different from insurance for an accountant or technology consultant.
3. Ask what insurers and policies are available
A broker may have access to products from multiple insurance companies.
4. Ask about exclusions
Understanding what is not covered can be just as important as understanding what is covered.
5. Ask about excesses
A lower premium may involve a different excess structure.
6. Review the policy wording
Do not rely solely on a verbal description of cover.
Business.gov.au notes that insurance policies are legal contracts and that the Product Disclosure Statement explains the policy's terms and conditions.
How to Choose Canberra Insurance Brokers for Your Business
Choosing a broker does not have to be complicated.
Start with your risks.
Step 1: Explain what your business does
Describe your services, customers, employees, premises and assets.
Step 2: Provide accurate financial information
Turnover and payroll figures can be important when arranging certain policies.
Step 3: Explain your contracts
Tell the broker if clients require specific insurance limits or policy wording.
Step 4: Discuss previous claims
Your claims history can be relevant when insurers assess risk.
Step 5: Review current insurance
If you already have policies, identify what's working and where changes may be required.
Step 6: Compare coverage, not just price
Two policies with similar premiums can have very different terms.
Step 7: Review every year
A growing business may outgrow its original insurance structure.
What Questions Should I Ask an Insurance Broker?
Before choosing an insurance broker in Canberra, ask practical questions.
What insurance do you think my business needs?
Ask the broker to explain why each policy is relevant.
What are the biggest exclusions?
This helps you understand where your business remains exposed.
How much cover should I consider?
Coverage limits should reflect your risks, contracts and assets.
What excess applies?
Understand what you may need to pay if you make a claim.
Can my policy be adjusted as the business grows?
Your insurance should be reviewed when circumstances change.
What happens when I need to make a claim?
Understand what assistance is available and who should be contacted.
Canberra Insurance Brokers and Local Service
For people searching “Canberra insurance brokers”, “insurance brokers Canberra” or “insurance broker ACT”, local availability can make communication easier, particularly when insurance involves detailed business information.
The Canberra Insurance Brokers website lists its office at Suite 173, M Centre, 11 Palmerston Lane, Griffith ACT 2603, with phone 1300 069 570 and email admin@canberrainsurancebrokers.com.au.
The business website currently lists services including business insurance, public liability, professional indemnity, cyber, commercial property, landlord, strata, transport, farm pack and boat insurance, among other options.
Its website identifies Earnest Insurance Pty Ltd as the entity trading as Canberra Insurance Brokers and states that it is a Corporate Representative of AJS Holding Co Pty Ltd AFSL No. 569591.
Before proceeding with any insurance purchase, customers should review the relevant licensing information, Product Disclosure Statement and policy wording.
Canberra Insurance Brokers for Businesses Across the ACT
Local search should not stop at the word Canberra.
Businesses and customers may also search based on nearby suburbs and commercial areas.
Relevant local searches include:
Canberra City
- insurance broker Canberra City
- business insurance Canberra City
- insurance brokers Canberra CBD
Griffith
- insurance broker Griffith ACT
- business insurance Griffith
- insurance brokers Griffith Canberra
Braddon
- insurance broker Braddon
- business insurance Braddon
- commercial insurance Braddon
Barton
- insurance broker Barton
- business insurance Barton ACT
- commercial insurance Barton
Belconnen
- insurance broker Belconnen
- business insurance Belconnen
- commercial insurance Belconnen
Woden
- insurance broker Woden
- business insurance Woden
- insurance brokers Woden
Fyshwick
- insurance broker Fyshwick
- commercial insurance Fyshwick
- business insurance Fyshwick
Hume
- insurance broker Hume ACT
- business insurance Hume
- commercial insurance Hume
Gungahlin
- insurance broker Gungahlin
- business insurance Gungahlin
- commercial insurance Gungahlin
Tuggeranong
- insurance broker Tuggeranong
- business insurance Tuggeranong
- insurance brokers Tuggeranong
These location-based searches reflect how people may look for services close to where they live, work or operate their business.
How Much Does an Insurance Broker Cost?
Another common question is whether using a broker costs more.
The answer depends on the broker's business model, insurance product and circumstances.
The more important question is what you receive in return.
A broker may help with:
- Identifying risks
- Comparing available options
- Explaining cover
- Reviewing policy documents
- Handling renewals
- Updating policies
- Supporting claims processes, depending on the service provided
Insurance costs themselves also vary according to the risk.
Factors can include:
- Industry
- Revenue
- Payroll
- Claims history
- Location
- Property value
- Number of employees
- Insurance limits
- Type of work
- Business activities
- Security and risk controls
There is therefore no universal price for using an insurance broker in Canberra or for purchasing a particular business insurance policy.
Why the Cheapest Insurance Quote May Not Be the Right Choice
Price naturally matters to every business.
But insurance exists to respond to financial risk, so price should not be the only comparison point.
Imagine two policies have similar premiums.
One has a higher coverage limit, while the other has broader exclusions.
One may include a particular extension that matters to your industry, while the other does not.
One may have a higher excess.
The policies might therefore provide very different levels of protection.
The better approach is to compare:
Premium + coverage + limits + exclusions + excess + conditions + insurer + claims process
That gives you a more meaningful picture than price alone.
When Should You Review Your Insurance?
A yearly insurance review is a sensible starting point, but you should also review your policies whenever the business changes.
Review your insurance when:
You hire employees
Your workers compensation obligations may be affected.
You move premises
Property, contents and liability exposures can change.
Your turnover increases
Some policies use financial information to determine premiums or coverage.
You purchase equipment
New assets may need to be added to your insurance.
You take on larger contracts
Contracts may require higher insurance limits.
You introduce new services
A new service can introduce a completely different risk.
You begin selling products
Product liability may become relevant.
You expand online
Cyber risk may increase.
You purchase vehicles
Commercial motor insurance requirements need to be reviewed.
Frequently Asked Questions About Canberra Insurance Brokers
What does an insurance broker do?
An insurance broker helps clients understand and arrange insurance products and may access policies from multiple insurers. Business.gov.au recommends using appropriately licensed brokers and checking AFS licensing information through ASIC.
How do I find an insurance broker near me?
Search for terms such as “insurance broker near me,” “insurance broker Canberra,” “insurance brokers Canberra” or “insurance broker ACT.” Then check the broker's location, licensing or authorisation information, insurance specialties, service offering and policy options.
What is the difference between an insurance broker and an insurance company?
An insurer underwrites the insurance policy and takes on the insured risk. A broker can help a client compare and arrange insurance with insurers, depending on the broker's market access and authorisations.
Do businesses in Canberra need insurance?
The insurance a business needs depends on its activities. The ACT Government identifies public liability, workers compensation and third-party personal injury insurance among common considerations, while professional indemnity, product liability, revenue, property, stock, assets and cyber insurance may also be relevant.
Is public liability insurance compulsory in Canberra?
Public liability is not automatically compulsory for every business. Certain occupations, activities, contracts or regulatory requirements may require it. Businesses should check requirements relevant to their circumstances.
Is workers compensation compulsory in the ACT?
Employers in the ACT must have a workers compensation policy covering their workers, subject to the applicable legislation and circumstances. WorkSafe ACT specifically states that workers compensation is separate from business and public liability insurance.
What insurance does a small business need?
There is no universal package. Common considerations include public liability, property, business interruption, professional indemnity, cyber and product liability, depending on the business.
Can an insurance broker help reduce my insurance costs?
A broker may help identify available options and compare policies, but no broker can guarantee a particular premium or savings. Insurance pricing depends on the business, risk profile, insurer and policy terms.
What should I take to my insurance broker?
Useful information includes business activities, turnover, payroll, employee numbers, assets, premises information, existing policies, claims history and any contracts specifying insurance requirements.
Should I choose a local Canberra insurance broker?
Location can be useful for face-to-face communication, but it should be considered alongside licensing, relevant experience, service, available insurance options and understanding of your business.
Finding an Insurance Broker in Canberra: A Practical Checklist
Before choosing an insurance broker ACT businesses can work with, check:
Licensing and authorisation
Confirm the relevant AFS licensing or representative information.
Industry experience
Ask whether the broker regularly works with businesses similar to yours.
Insurance options
Understand which insurers and products may be available.
Communication
Choose a broker relationship where coverage and exclusions are clearly explained.
Claims assistance
Ask how claims are handled and what support is offered.
Policy reviews
Make sure there is a process for reviewing your insurance as your business changes.
Documentation
Always obtain and review the relevant PDS and policy wording.
Final Thoughts: Choosing Canberra Insurance Brokers
Searching for Canberra insurance brokers, insurance broker Canberra, insurance brokers Canberra, insurance broker ACT, insurance brokers or even insurance broker near me is only the beginning.
The real question is whether the insurance solution matches your circumstances.
A business owner should understand what risks could create the greatest financial impact and then consider appropriate ways to manage those risks.
For some Canberra businesses, public liability may be central.
For professional services firms, professional indemnity may be critical.
For property owners, commercial property and loss-of-income considerations may deserve attention.
For technology-dependent businesses, cyber risk may need a closer look.
For employers, ACT workers compensation requirements must be addressed.
And for many businesses, the appropriate solution is a combination of several policies rather than one standalone insurance product.
The role of an insurance broker is therefore not simply about finding a quote.
It is about helping you navigate the insurance process, understand your available options and review whether your cover continues to match your business as it grows.
For businesses and customers in Canberra and the Australian Capital Territory, Canberra Insurance Brokers provides information and insurance options covering areas such as business insurance, public liability, professional indemnity, cyber, commercial property and other insurance products.
When comparing an insurance broker, look beyond the headline price. Check the relevant authorisation, understand the policy, compare limits and exclusions, and read the Product Disclosure Statement before making a decision.
Need help reviewing your insurance options in Canberra? Canberra Insurance Brokers lists its Griffith ACT office at Suite 173, M Centre, 11 Palmerston Lane, Griffith ACT 2603 and provides contact details through its website.






Get in Touch With Us
Have questions about insurance? Our experienced brokers are here to help you find the right coverage.